Fee-Only Retirement
Income Planning
You spent a working lifetime building savings. The next question is how to turn those accounts into steady, tax-aware income. We answer it as an independent, fee-only planning firm, paid only by our clients, never by commissions or product sales.
Request a Retirement Income Consultation- 100% Fee-Only, No Commissions
- Since 1996 Independent Registered Investment Adviser
- CFP® Jamie Milne, CERTIFIED FINANCIAL PLANNER™ Professional
- 2 Offices Winooski and St. Johnsbury, Vermont
Turning a Lifetime of Savings into Income You Can Count On
Retirement income planning answers a different question than saving for retirement did. Instead of asking how much to put away, it asks which account to draw from first, when to claim Social Security, how much tax each withdrawal triggers, and what happens to that income if markets fall in your first few years of retirement.
Those decisions interlock. Claiming Social Security early can change how much of an IRA withdrawal is taxed. A large distribution in one year can raise a Medicare premium two years later. A Roth conversion done in a low-income year can lower taxes for a decade. Handled one at a time, these choices often work against each other. Handled together, they form a plan.
We build that plan as an independent, fee-only firm. One hundred percent of our compensation comes from our clients. We sell no products and accept no commissions, so there is no version of this work where a recommendation pays us more than the alternative. For the broader picture, start with our retirement planning services, or read what sets a fee-only firm apart on the MFP difference.
Why Retirement Income Deserves a Plan of Its Own
The rules that govern retirement income are set by other people, and most of them run on deadlines. Knowing the deadlines early is what turns a pile of accounts into a paycheck.
Social Security Timing Is Mostly Permanent
Delaying benefits past full retirement age earns delayed retirement credits, which the Social Security Administration sets at 8 percent per year up to age 70 (Social Security Administration, SSA Handbook section 720). Claiming earlier reduces the monthly benefit for life. The right answer depends on your other income, your health, and your spouse's record, and it is worth modeling before you file.
Taxes Do Not Retire When You Do
Required minimum distributions from traditional IRAs and most workplace plans generally begin at age 73 for people born between 1951 and 1959, and at 75 for those born in 1960 or later (Internal Revenue Service). Those withdrawals are taxable whether or not you need the money, which is why the years before they start are often the most useful planning window you have.
Withdrawal Order Changes the Tax Bill
Taxable, tax-deferred, and Roth accounts are taxed differently, so the order you draw from them shapes what you keep. Sequencing also affects how much of your Social Security benefit is taxed and which Medicare premium bracket you land in. These effects compound across a 25 or 30 year retirement.
How Advice Is Paid for Shapes the Advice
Retirement income is the stage of life where commission-based products are most often sold. Because we are fee-only, we are paid by our clients and by no one else. We do not sell investment or insurance products, so a recommendation to keep things simple costs us exactly the same as a recommendation to buy something.
Our Fee-Only Retirement
Income Services
You can work with us once, for a plan you carry out yourself, or on an ongoing basis. Either way the fee is agreed in advance and paid by you, and the advice is the same.
Retirement Income and Withdrawal Strategy
We map your accounts, pensions, and expected expenses, then build a year by year withdrawal order designed to support your spending while managing the tax you pay to get there.
Social Security and Pension Timing
We model claiming ages side by side, including spousal and survivor outcomes, so the filing decision is made with the numbers in front of you rather than on a rule of thumb.
Roth Conversion Analysis
The window between retiring and starting required withdrawals is often the lowest-tax stretch of your life. We look at whether converting in those years helps or hurts.
Roth conversionsTax-Aware Distribution Planning
Retirement income decisions and tax decisions are the same decisions. We coordinate withdrawals, capital gains, and charitable giving with your tax picture for the year.
Tax planningInvestment Management for Income
For clients who want us to manage the portfolio, we align the investments with the income the plan calls for, including how much to hold in reserve for near-term withdrawals.
Ongoing management services and feesOne-Time Retirement Income Review
Prefer to handle the implementation yourself? We offer a flat-fee review that gives you the analysis, the recommendations, and a written plan, with no requirement to move your accounts.
One-time services and feesNot sure which fits? A one-time financial plan review is a common starting point, and our retirement planning services page covers the wider plan this income strategy sits inside.
Why Retirees Work with a Fee-Only Planner
Retirement income is the point where the way an advisor is paid stops being a technicality. Every dollar you move in these years has a tax consequence and, in a commission model, a potential sales consequence too.
We removed the second one. Our compensation comes from our clients, in fees agreed before any work begins, and from nowhere else.
- ✓
Fee-Only by Choice
We accept no commissions and sell no investment or insurance products. One hundred percent of our compensation is paid by our clients.
- ✓
A Fiduciary Standard in Our Advisory Work
Our advisory recommendations are made in your best interest, which is the standard we have operated under as a Registered Investment Adviser.
- ✓
Independent Since 1996
No parent company, no proprietary product shelf, and no sales targets. The firm answers to its clients.
- ✓
Rooted in Vermont
Offices in Winooski and St. Johnsbury, with clients across Vermont and New Hampshire who can sit down with us in person.
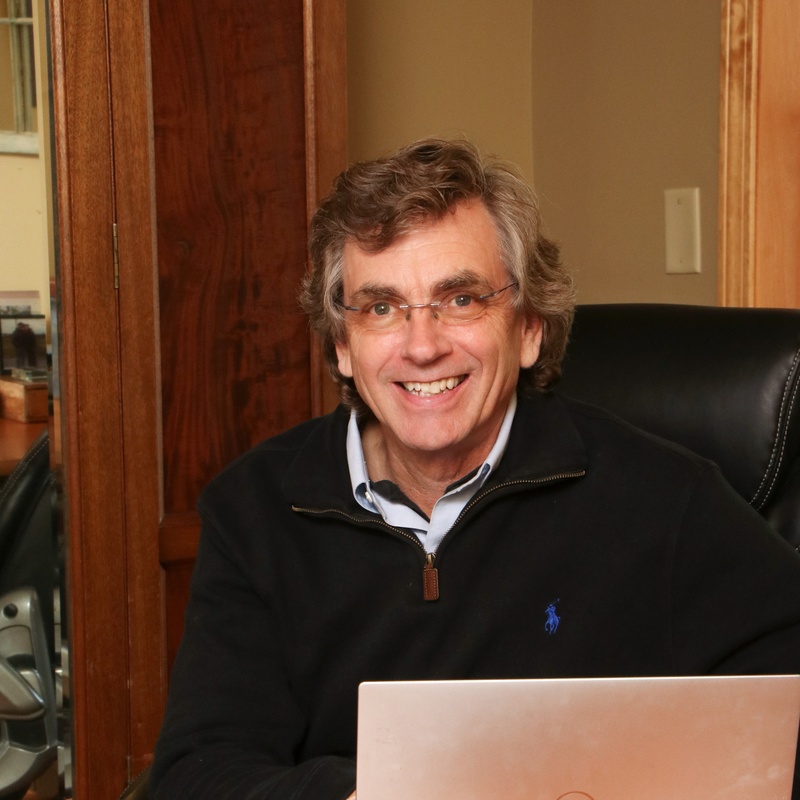
Jamie Milne, CFP®
After working in banking and insurance, Jamie started Milne Financial Planning in 1996 to build a completely independent firm. He is a CERTIFIED FINANCIAL PLANNER™ professional, takes his fiduciary oath seriously, and keeps the firm fee-only by choice so recommendations stay free of product compensation conflicts.
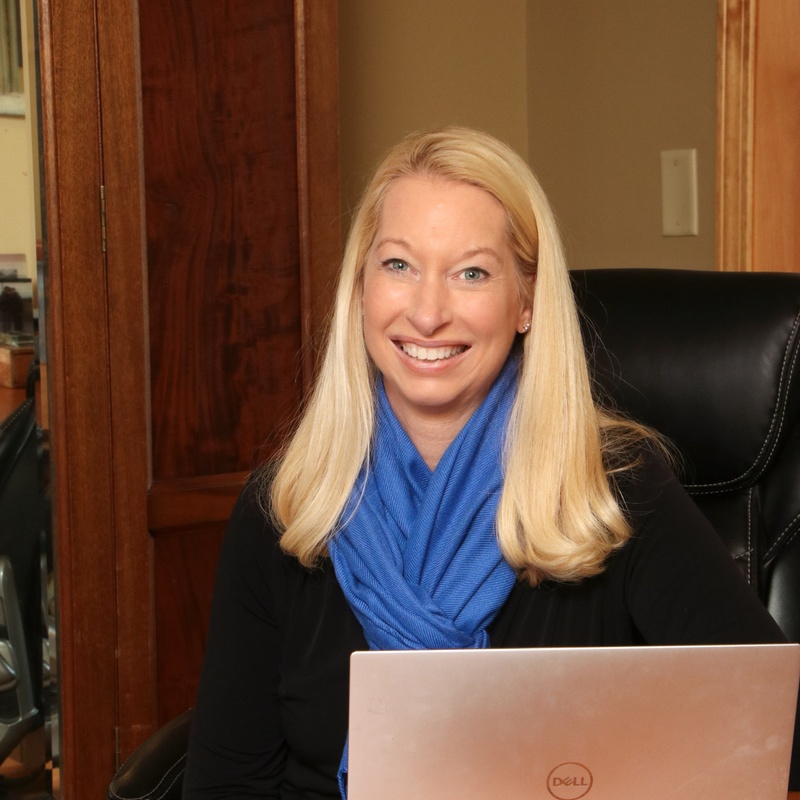
Katheryn Milne
Katheryn makes sure clients feel supported and well cared for, answering questions and coordinating follow-up between meetings. A Certified Public Accountant licensed in Vermont, she brings a detailed financial background and a lifelong Vermonter's perspective to the client relationship.
Areas We Serve
We meet clients at our Winooski and St. Johnsbury offices, and by phone and video for those further afield.
- Greater Burlington and Winooski, VT
- St. Johnsbury and the Northeast Kingdom
- Montpelier and central Vermont
- Communities across New Hampshire
- Northern New England statewide
Winooski Office
20 West Canal Street, Suite C13
Winooski, VT 05404
St. Johnsbury Office
770 Railroad Street
St. Johnsbury, VT 05819
Request a Fee-Only Retirement Income Consultation
If you are within a few years of retirement, or already drawing from your accounts and wondering whether the order is right, a conversation is the place to start. We will talk through where your income will come from, what the tax picture looks like, and whether a one-time plan or ongoing management fits you better.
No products are sold in this conversation, because we do not sell any.
Frequently Asked Questions
What is retirement income planning?
Retirement income planning is the process of turning savings into dependable income once the paychecks stop. It covers which accounts to draw from and in what order, when to claim Social Security or a pension, how much tax each withdrawal creates, and how the plan holds up if markets fall early in retirement.
How is retirement income planning different from retirement planning?
Retirement planning is the broader picture, including how much to save and when you can afford to stop working. Retirement income planning picks up at the transition and focuses on the distribution years, where the questions are about withdrawal order, claiming timing, and taxes rather than accumulation.
What does fee-only mean, and why does it matter for retirement income?
Fee-only means one hundred percent of our compensation is paid by our clients. We accept no commissions and sell no investment or insurance products. It matters most in the distribution years, because that is when commission-based products are most often sold to retirees, and a fee-only firm has no financial reason to recommend one.
When should I start retirement income planning?
Many people benefit from starting three to five years before they retire, while there is still time to adjust savings, coordinate a spouse's timing, and use lower-income years for strategies such as Roth conversions. It is still worth doing after you retire, because withdrawal order and tax decisions come up every year.
Do I have to move my accounts to work with you?
No. We offer one-time, flat-fee planning for people who want the analysis and a written plan to carry out themselves, and ongoing management for those who prefer that we handle the investments. The fee is agreed in advance either way.
Do you work with clients outside Vermont?
Yes. Our offices are in Winooski and St. Johnsbury, Vermont, and we work with clients across Vermont and New Hampshire, including meetings by phone and video. Contact us to confirm that we can serve your state before any work begins.